
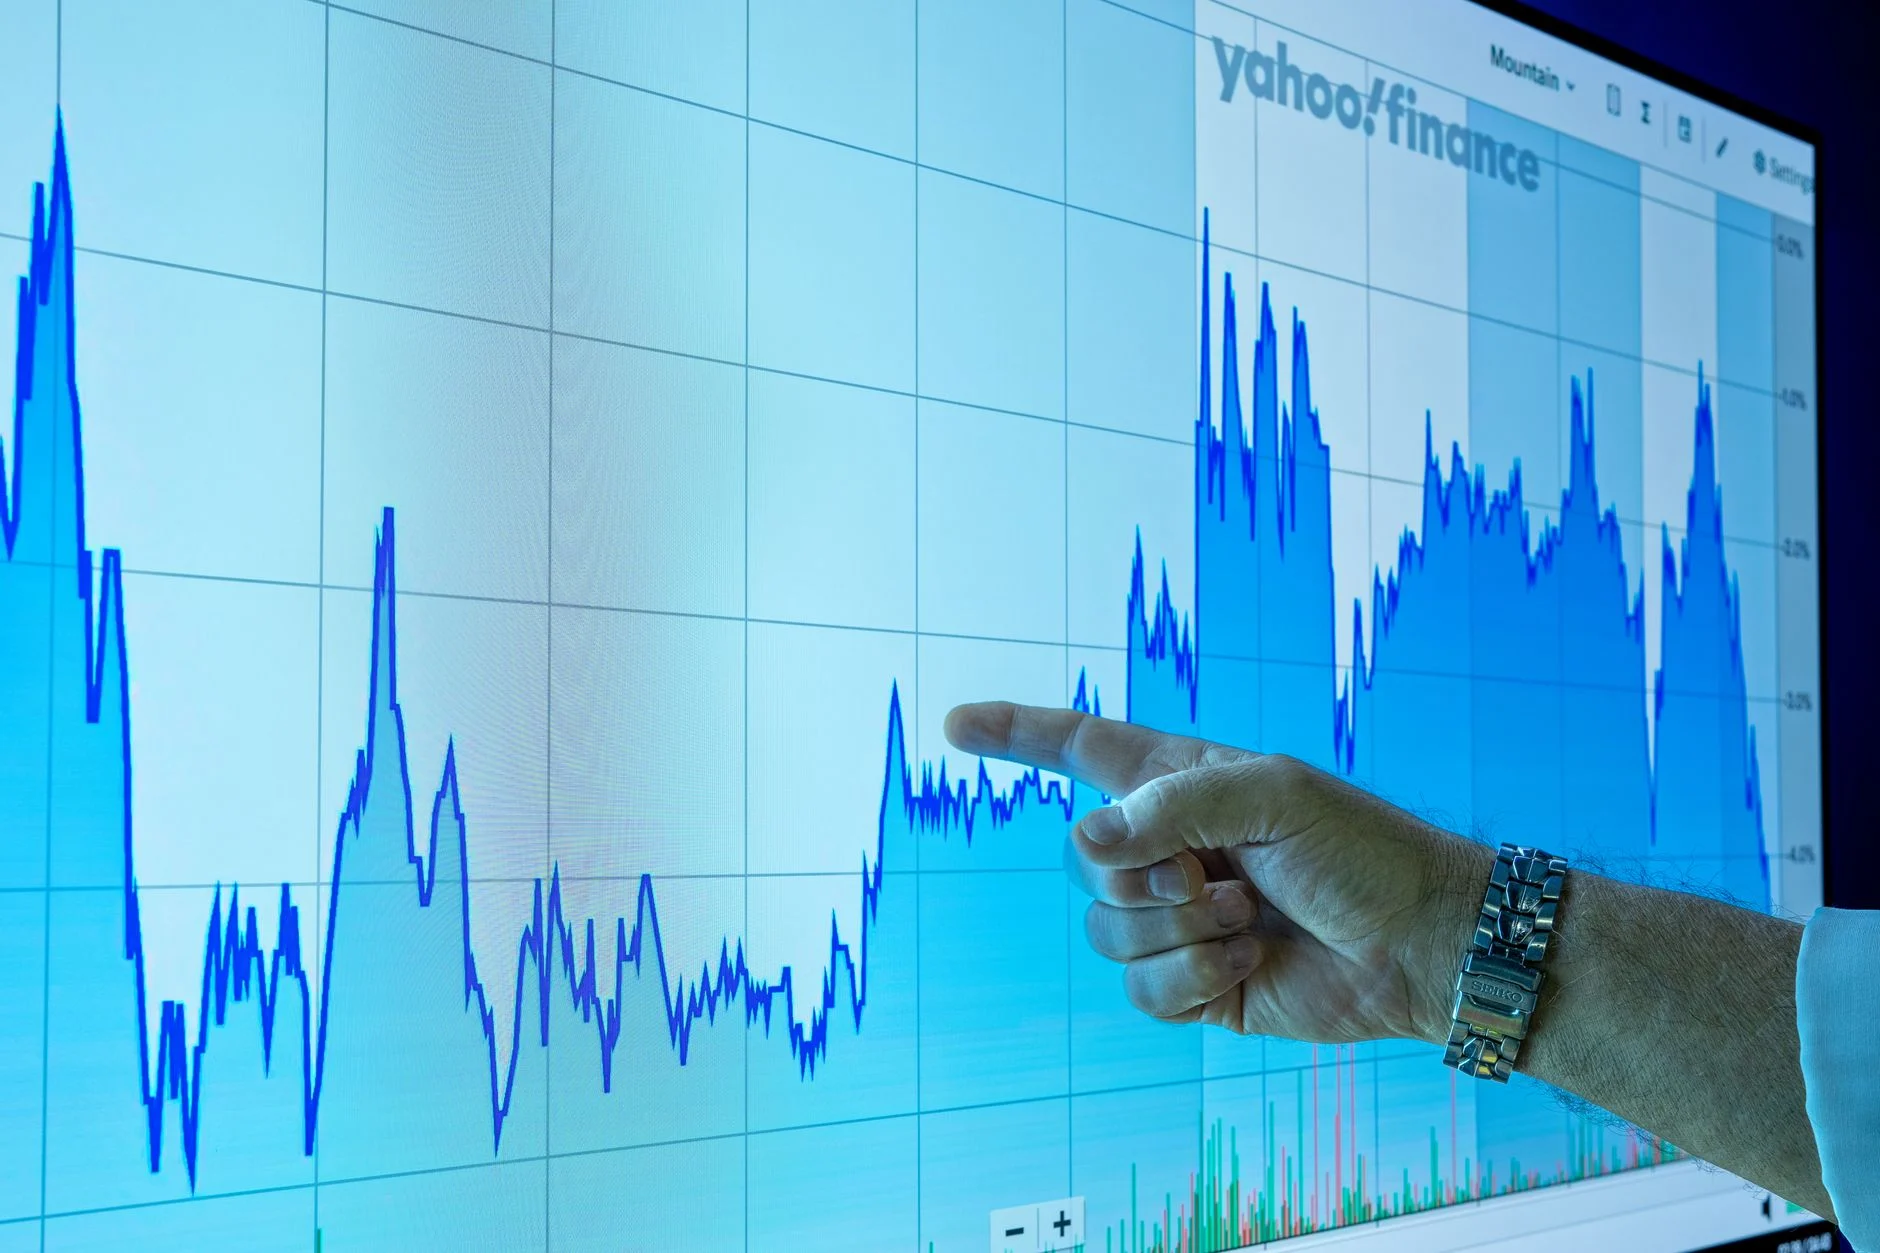
- Rising bond yields and elevated oil prices evoke late-1990s market dynamics without replicating the dot-com bubble’s extremes.
- Wall Street advisors emphasize long-term equity exposure to navigate volatility driven by macroeconomic shifts.
- Structural changes in corporate earnings and monetary policy differentiate current conditions from the 1999–2000 bubble burst.
- Investors face trade-offs balancing inflation risks against growth opportunities amid evolving geopolitical tensions.
What happened
Recent market developments have prompted comparisons to the late 1990s dot-com bubble, with notable increases in U.S. Treasury yields and a sustained surge in energy prices. Bond yields have breached levels not seen in over a decade, reflecting expectations of prolonged inflation and tighter monetary policy. Concurrently, oil prices remain elevated due to a combination of geopolitical uncertainties and supply constraints. These shifts have unsettled equity markets, particularly growth-oriented segments reminiscent of the technology-heavy valuations of the dot-com era. Despite this, prominent Wall Street advisors are urging investors to maintain their equity positions rather than retreat to safer assets.
Why it matters
The current environment tests conventional investment wisdom, as rising yields typically pressure equity valuations through higher discount rates, while energy price inflation can squeeze corporate margins and consumer spending. The comparison to the 1999–2000 bubble raises concerns about a potential market correction or a broader economic downturn. However, the decision by financial professionals to recommend staying invested underscores a nuanced assessment of risk and opportunity. This stance influences asset allocation strategies across retail and institutional investors, shaping capital flows and market stability globally. Understanding the rationale behind this counsel is critical for navigating what might otherwise be interpreted as a forewarning of systemic fragility.
Industry context
The late 1990s marked a period of exuberant technology stock valuations fueled by speculative investment in internet ventures, facilitated by loose monetary policy and nascent digital infrastructure. The subsequent bubble burst led to a sharp market downturn and a reevaluation of growth prospects. Today’s environment shares superficial similarities—high valuations in growth sectors, rising bond yields, and inflationary pressures—but diverges in several key respects. Monetary policy is more proactive, with central banks signaling gradual rate increases rather than abrupt hikes. Corporate earnings are generally more robust and diversified across industries, supported by technological adoption and global supply chains. Moreover, energy markets are influenced by geopolitical factors distinct from the technology-driven optimism of the late 1990s.
Analysis
The decision to remain invested amid these conditions hinges on several intersecting mechanisms. Firstly, rising bond yields increase the cost of capital, pressuring discount rates applied to future earnings. Yet, current earnings growth—bolstered by sectors such as industrials, consumer staples, and energy—provides a counterbalance that was less prevalent during the dot-com bubble. Secondly, inflationary pressures, while significant, are partially offset by companies’ ability to pass costs to consumers, maintaining profit margins. Thirdly, monetary policy trajectories suggest a measured approach aimed at taming inflation without triggering recession, contrasting with the abrupt tightening that punctuated past market corrections.
Furthermore, geopolitical tensions impacting energy prices introduce complexities absent from the 1990s landscape. These factors increase market volatility but also create investment opportunities in sectors aligned with energy transition and supply chain resilience. Advisors emphasize diversification and active management to navigate these dynamics rather than wholesale withdrawal from equities. This reflects a recognition that market corrections are inherent to equity investing, and timing exits and re-entries often proves more detrimental than enduring volatility.
What to watch next
Key indicators will shape whether the current market environment evolves into a sustained downturn or stabilizes as advisors anticipate. Monitoring central bank communications and policy actions will be crucial to gauge the pace and magnitude of interest rate adjustments. Inflation data, particularly core measures excluding volatile energy components, will influence monetary decisions and investor sentiment. Energy market developments—such as shifts in OPEC+ strategies or geopolitical escalations—will affect both inflation and corporate profitability.
Equally important will be corporate earnings reports, especially among growth sectors sensitive to discount-rate changes. Investors should also watch for shifts in market breadth and liquidity, which can presage broader risk-off behavior. Ultimately, the interplay between macroeconomic fundamentals and geopolitical factors will determine whether the parallels to the dot-com era represent a historical echo or a false alarm.
Ask AI about this story
Answers are based on this article and SN Media’s related coverage. AI can make mistakes.
Frequently asked questions
Why are Wall Street advisors recommending staying invested despite comparisons to the dot-com bubble?
Advisors emphasize long-term equity exposure due to structural differences from the dot-com era, including more robust and diversified corporate earnings and a more measured monetary policy approach, which together mitigate the risks seen in the late 1990s.
How do current market conditions differ from those during the 1999u20132000 dot-com bubble?
Unlike the dot-com bubble, todayu2019s market features proactive central bank policies with gradual rate increases, stronger corporate earnings across various sectors, and geopolitical factors influencing energy prices, rather than technology-driven speculative excess.
What are the main risks and opportunities investors face in the current environment?
Investors must balance inflation risks and rising bond yields against growth opportunities supported by sectors like industrials and energy, with geopolitical tensions adding volatility but also creating investment prospects in energy transition and supply chain resilience.
What indicators should investors monitor to understand future market direction?
Key indicators include central bank policy signals, inflation data excluding volatile energy components, developments in energy markets, corporate earnings reports especially in growth sectors, and market liquidity and breadth to detect shifts toward risk-off behavior.
Continue the story
 LATEST
Balancing Act: How Rising Yields Threaten the AI-Driven Tech Rally on Wall Street
- LATEST Decoding the Bond Market’s Selloff: What Wall Street’s Latest Signal Means for Investors
- LATEST How Cross-Asset Hedging Is Reshaping Investment Strategies Amid Market Uncertainty
- LATEST How Falling Oil Prices Are Reshaping US Stock Market Sentiment
- LATEST S&P 500’s Resurgence: What It Means for Global Economic Stability